Quick Summary: EIS vs VCT
What is the Enterprise Investment Scheme (EIS)?
The Enterprise Investment Scheme (EIS), which has operated since 1994, saw 3,735 companies raise £1.575 billion in the 2024/25 tax year, according to HMRC’s May 2026 statistics.
The reliefs are the widest of any UK venture scheme: income tax relief on subscription, tax-free growth on a qualifying disposal, deferral of a capital gain made elsewhere, loss relief if the company fails, and potential inheritance tax treatment through Business Relief where the qualifying conditions are satisfied.
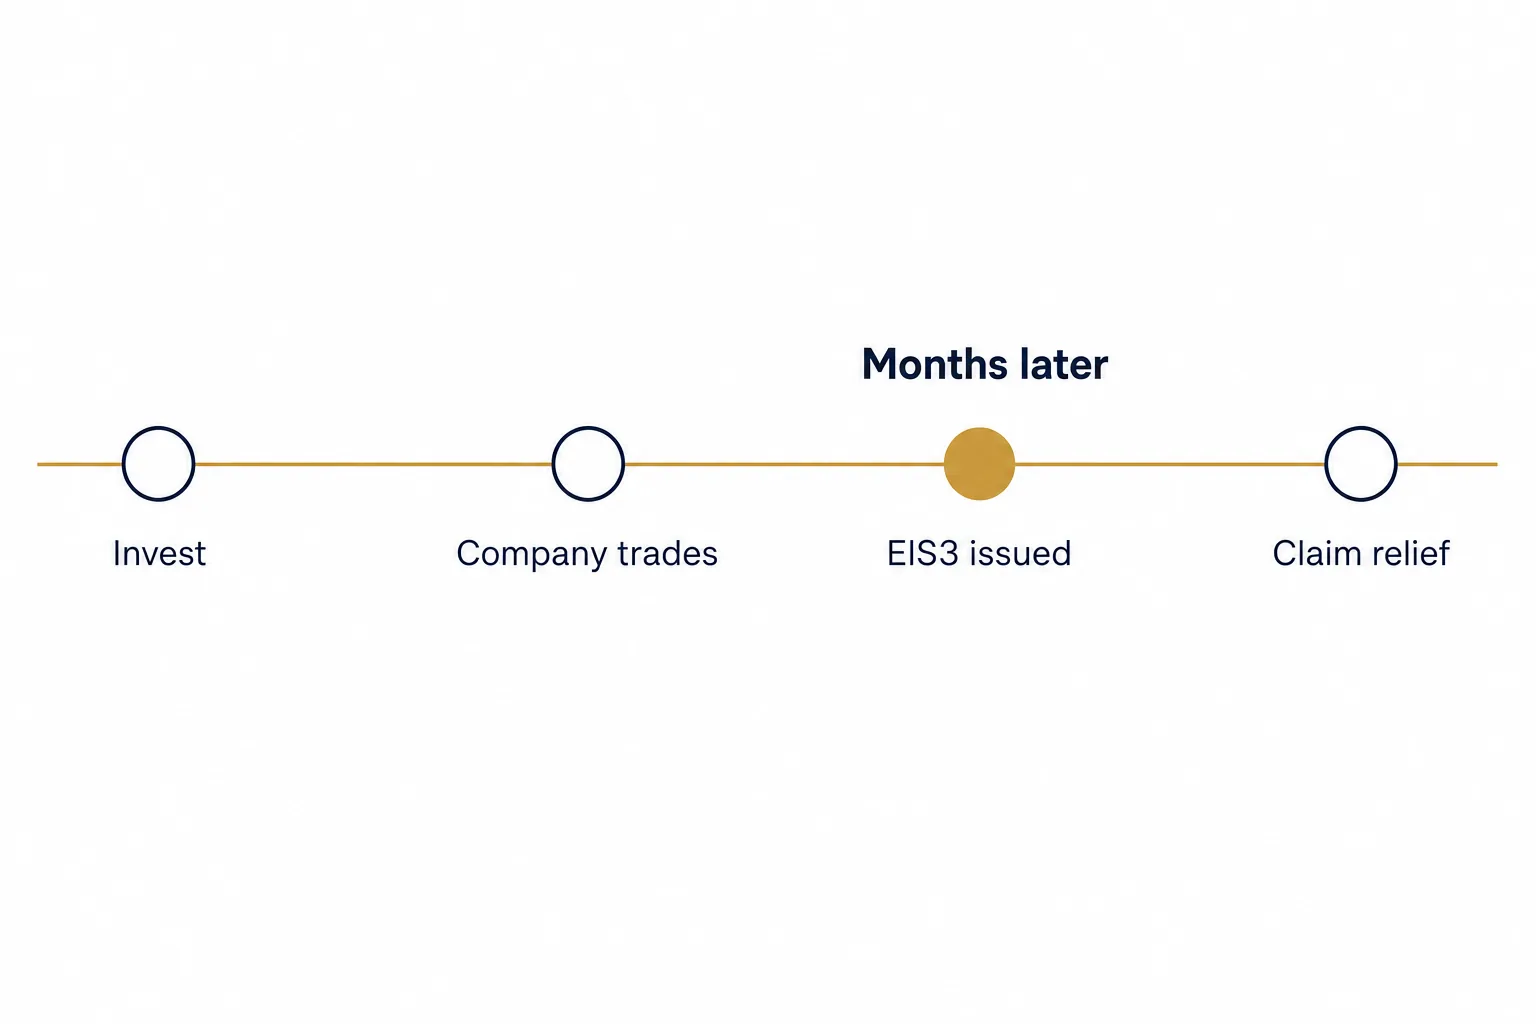
One practical point catches people out. You cannot claim income tax relief the moment you invest. The company issues an EIS3 certificate only once it has traded for the required period, which often means waiting months after the money leaves your account.
What is a Venture Capital Trust (VCT)?
A VCT is a closed-ended company listed on the London Stock Exchange and run by a professional manager, usually holding dozens of qualifying businesses at different stages of maturity. You own shares in the trust, not in any of the underlying companies, so you never make a company-by-company decision.
The reliefs are narrower but simpler: income tax relief on subscriptions for new VCT shares, tax-free dividends, and no capital gains tax on growth in the VCT share price. There is no gain deferral, no loss relief and no Business Relief.
The paperwork is simpler than EIS, too. A VCT investment produces one share certificate, usually within weeks, rather than the several EIS3 certificates that can take months to arrive across a diversified EIS portfolio.
EIS vs VCT comparison table
| EIS | VCT | |
|---|---|---|
| What you own | Shares in individual unquoted companies | Shares in a listed trust holding a portfolio |
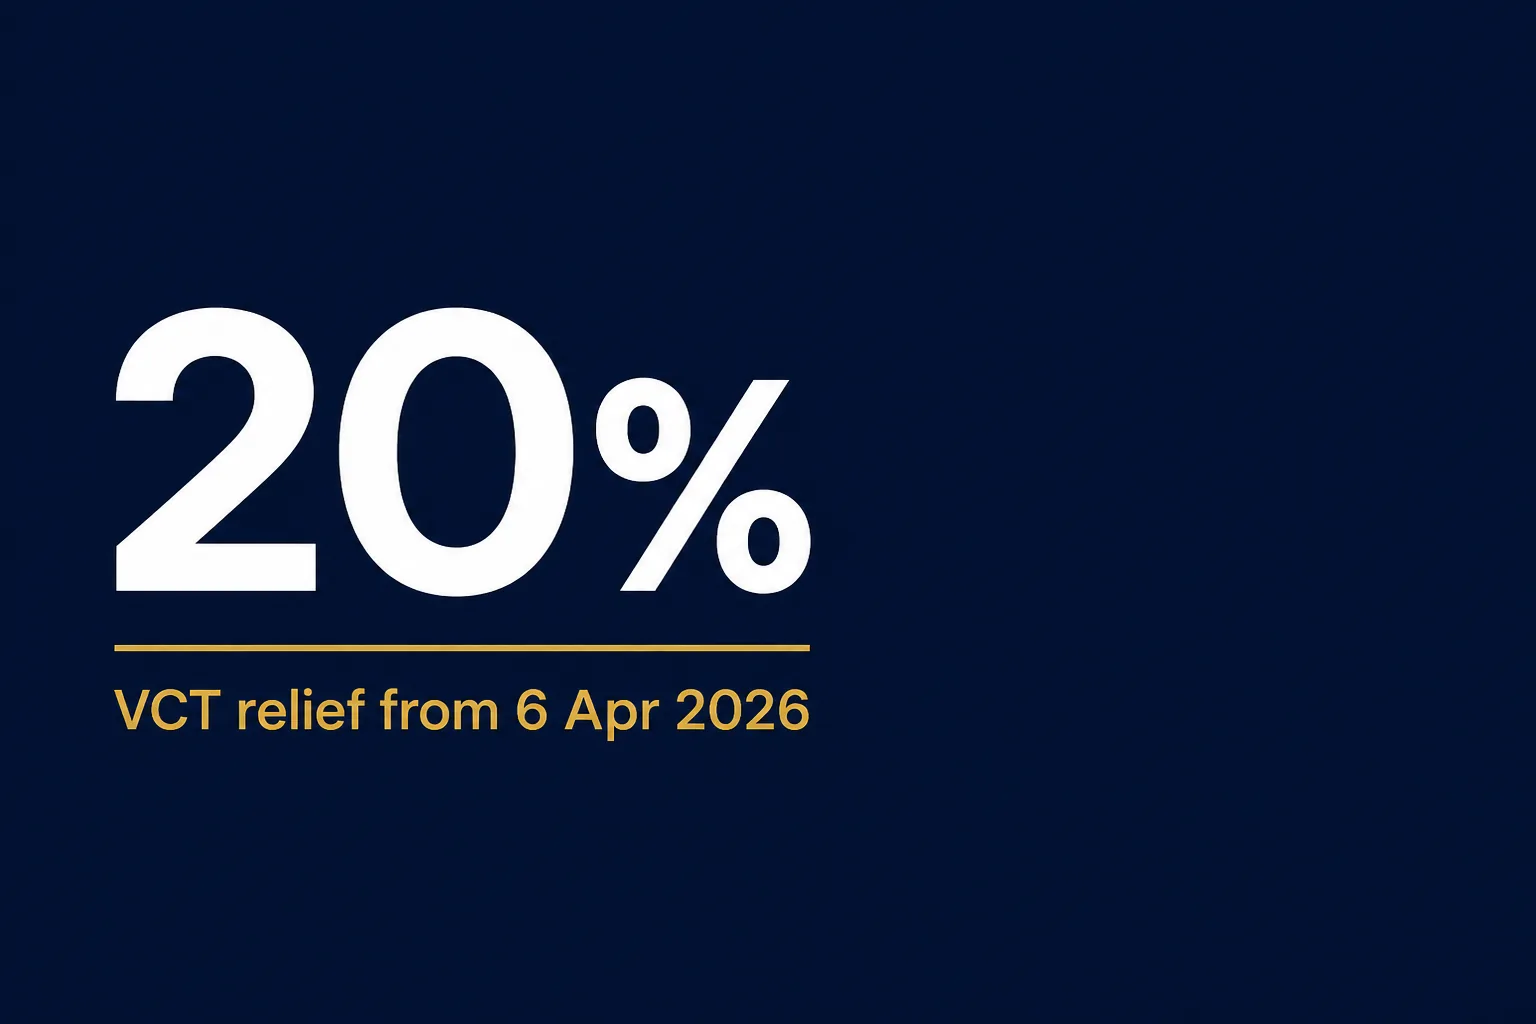
| Income tax relief | 30% | 30% now, 20% on new subscriptions from 6 April 2026 |
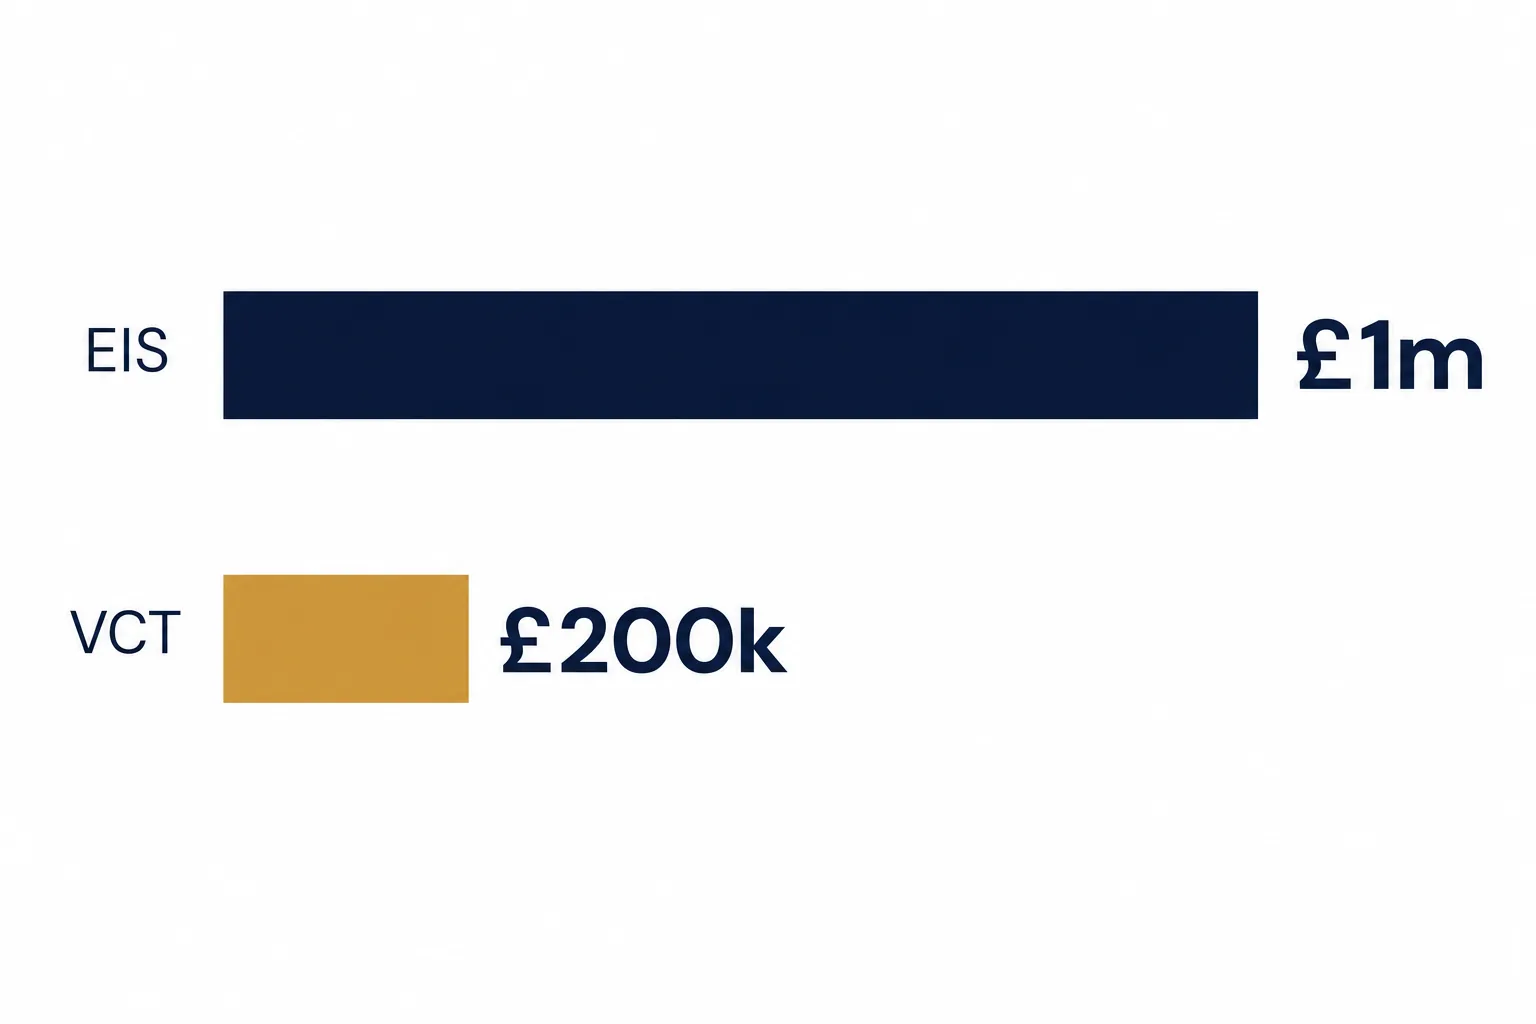
| Annual investment limit | £1m, or £2m including knowledge-intensive companies | £200,000 (the cap itself is unchanged; only the 30% relief rate drops to 20% from 6 April 2026) |
| Minimum holding period | 3 years | 5 years |
| Dividends | Rare in practice | Tax-free, but variable |
| Gains on disposal | Tax-free on qualifying shares | Tax-free on VCT shares |
| CGT deferral | Yes | No |
| Loss relief | Yes, company by company | No |
| IHT Business Relief | Possible, subject to qualifying conditions | No |
| Diversification | You build it yourself | Built in |
| Liquidity | None until an exit | Listed, but thinly traded |
| Carry-back to prior year | Yes | No |
Rules change, and one change is already on the statute book: the legislated cut to VCT income tax relief takes effect on 6 April 2026. Check the current position before you commit.
EIS vs VCT: where the tax reliefs really diverge
Income tax relief and annual limits
The headline rate has historically been the same, but the ceilings are not close. HMRC’s venture capital scheme relief limits set EIS income tax relief at 30% on up to £1 million per tax year, rising to £2 million where at least £1 million of that goes into knowledge-intensive companies. VCT subscriptions are capped far lower, and the reduction from 30% to 20% on new VCT shares narrows the gap further from April 2026.
Two things decide what that relief is worth to you. Relief cannot exceed the income tax you owe, so a modest tax bill caps the benefit however much you invest. And EIS lets you carry relief back to the previous tax year. VCTs do not.
Income versus growth: dividends and capital gains
VCTs are engineered for income. Dividends are usually paid out of realised gains in the portfolio, arrive tax-free, and need no entry on your tax return. They are also variable. A quiet year for exits is a quiet year for dividends.
EIS pays nothing along the way. The return, if there is one, is a single exit event that can take many years and sometimes never comes. Against that, only EIS lets you defer a capital gain crystallised elsewhere, which is why investors who have just sold a property or a business often look at EIS first.
Downside protection: loss relief and IHT
EIS loss relief works company by company, which changes the shape of the downside. Invest £10,000, claim 30% relief, and £7,000 is at risk. If that holding goes to zero, loss relief can be set against income at your marginal rate, cutting the net cost again. The arithmetic depends on your tax position and on the relief being available and correctly claimed.
VCTs have no equivalent. Losses are absorbed inside the trust and netted against the winners before anything reaches you.
That relief runs on its own clock, separate from the three-year EIS holding period: shares generally need to be held for two years to qualify. It has also just got smaller.
From 6 April 2026, 100% Business Relief on qualifying unquoted shares is capped at £2.5 million per person, combined with agricultural property relief. Anything above that allowance is taxed at an effective 20% rate rather than passing free of inheritance tax.
A VCT gives you a spread across dozens of businesses from a single decision. One EIS subscription gives you one company. Some share of any early-stage portfolio is expected to fail, so EIS investors build diversification deliberately: several companies, several sectors, staged across tax years rather than crammed into one March rush.
Can you lose money? Yes, including all of it.
Loss relief softens the blow; it does not remove it.
Holding periods differ, and so do the consequences of breaking them.
| EIS (sold before 3 years) | VCT (sold before 5 years) | |
|---|---|---|
| Income tax relief | Withdrawn | Clawed back |
| Deferred capital gain | Crystallises immediately | Not applicable, VCT carries no CGT deferral relief |
| CGT exemption on growth | Lost | Not affected, there’s no minimum holding period on VCT’s CGT exemption |
On liquidity, VCT shares are listed but thinly traded and often change hands below net asset value. EIS shares have no market at all until an exit.
Scheme longevity is settled for now: the government has extended the EIS and VCT sunset clauses to 6 April 2035, which matters if your exit horizon is a decade out.
Which one suits which investor?
Lean EIS if you:
- Have a capital gain to defer
- Want the greatest growth potential
- Value loss relief on individual holdings
- Are thinking about inheritance tax planning
- Can leave the money alone for several years
Lean VCT if you:
- Want tax-free income now
- Prefer one decision over twenty
- Want a defined five-year holding period
- Want a listed exit route, however imperfect
It is rarely either/or. Plenty of investors run both, using VCTs for income and EIS for growth and gain deferral, and the annual limits are separate. The binding constraint is usually your income tax liability and your genuine capacity for loss, not the scheme rules. This article is educational and is not personal advice; check suitability with a qualified adviser.
Beyond the tax wrapper: investing in private companies well
The relief is the wrapper. The company is the investment. No amount of tax relief rescues a business with no customers, and this is the part most comparisons skip.
The questions are the same on both routes. What has the founding team actually built before? Is there revenue, or only a forecast? What precisely is this round funding, and how many months of runway does it buy? Who buys this company at the end, and at what kind of multiple? How far will the rounds that follow dilute you?
Beaufort Society is a private equity firm with an investor club attached. It is free to join, and we are paid an introducer fee by the company raising the funds, not by our members. That structure is why we can spend the time explaining a deal rather than selling it. Members see curated opportunities that are not posted on open angel platforms, plus the market context to make sense of them. If you are working out how to invest in private companies and want to ask questions before committing anything, that is what the club is for.
Related readingHow to Invest in Unlisted Companies in the UKRead the guide →